Featured post

What Do High Growth Businesses Do Differently?

Over the past 5 years the importance of the “High Growth Business” and how this relatively small group of businesses disproportionally impa...

Showing posts with label small business. Show all posts

Wednesday, 6 May 2015

Are You Squeezing the Lemon?

I've seen in recent weeks a whole raft of articles and blogs about the need to grow your business and how you can grow sales by using various channels from Facebook to plain old cold calling. As usual this is the easy target because most businesses have a need to get more sales.

I thought therefore it would be interesting to focus on a different area of the business and one which can just as easily wipe out your profits as a lack of sales. That is your the processes you use to deliver what you sell and collect money from your customers. I call it squeezing the lemon because in or to help maximise your profits you need to squeeze every once of efficiency and productivity out of you delivery systems.

Are You Squeezing the Lemon?

The problem is often that this is the part of business operations that is often overlooked. As is collection of money. In a recession we all say that cash is kind, but its no different now that things have improved. Almost invariably as sales improve the focus moves away from collecting the money. This is the equivalent of restricting the supply of oxygen to a mountain climber. Yes they might manage to go on but it just makes it a lot harder, and is so unnecessary.

The most obvious measure is your debtor days which is simply the amount of money currently outstanding divided by your current turnover times 365. Your objective then is to keep your debtors days don as low as possible. This keeps cash regularly flowing back into your business and will support further growth.

Squeezing the Lemon isn't just about cash but your whole production and sales support processes.
For example, its making sure that you keep your product delivery times the same, and that you don't allow your quality to be compromised. Or that you have sufficient resources to deliver the same or better quality of proposals to the increased enquiries from customers and prospects.

How might you do this? I know a number of accountants have an ability to benchmark your business against similar organisations in your industry. This will give you a broad areas where you over or under perform your industry average.  If you accountant can't help you then its up to you to start finding out how your business is performing. You can do this by setting clear targets, often called KPI's, about the expected performance of parts of your business. I would suggest that you should be setting KPI's for your business anyway.
This could be as simple as:
The average response time for a query into the business.
The average time to produce proposals.
The target time to produce a sub-component.
The target for the percentage of goods delivered on time
The target for the level of customer experience

The key point here is not to take your eye off doing the basics properly and as efficiently as possible. Even a small, 5%, fall off in performance in a couple of areas can have a material impact on your bottom line.

For example, I worked in an automotive business and we had regular quarterly meeting to`see if we could reduce the time taken to produce our 10 biggest sellers. We were often able to save 1% in time by making changes to how we manufactured the components. That's 4% per year, but measured over 10's of thousands of items it has a big impact and can often be the difference between making a loss and making a profit.

The thing about Squeezing the Lemon is that you are constantly looking for improvements in performance to minimise the your costs of production. Normally we all focus on this in a downturn because with lower sales we must reduce costs. By contrast, as soon as sales rise we have a tendency to put efficiency on the back burner. Surely it makes sense to keep squeezing the lemon even when sales are up.


Exigent Consulting provides specialist services for Managing High Growth, Business Turnaround, and Mentoring to the Small and Medium Business. We help business owners improve the profit performance of their business. 


Monday, 15 December 2014

Is This the Worlds Worst Sales Qualification Question?

Over recent weeks I've seen many businesses fall into this trap and rely on what I think is the world worst sales qualification question. It seems to be especially prevalent in micro businesses and in the creative industries.

In my opinion sales qualification is one of the most important aspects of closing sales. Unfortunately these days most experts seem to concentrate on closing, however proper sales qualification makes sales closing easier. Good sales qualification will help you identify early in the sales cycle those prospects most likely to commit to buy from you, and at the same time help you shorten the sales cycle. Something that we all want. Poor sales qualification, by contrast, results in the opposite leading to a lot of wasted effort and fewer sales.
English: Priit Narusk in the qualification for...
 Priit Narusk in the qualification for the Tour de Ski in Prague.  (Photo credit: Wikipedia)

As we come out of our sluggish economy the number of sales opportunities increases as potential buyers prepare to invest. As providers of products and services we enjoy more sales conversations unfortunately this new found wealth of prospects is ruined by one single question which kills time and is our own work creation scheme. On the face of it this question seems quite sensible and for the inexperienced sales person a good one. Nothing can be further from the truth. 

The culprit for this colossal waste of time the question "Can I write you a proposal".

Why? The answer to this question is almost invariably "yes" so off you go thinking that you’ve progressed the sale because they want you to write a proposal. In reality you've done no such thing. Ask anyone if you can write them a proposal, ask your mates, your competition even the bloke on the corner, they'll all say yes because that question means nothing. Knock yourself out, write me a proposal, in fact send me three because that question commits me to absolutely nothing but creates a whole lot of work for you. What you have really asked me for is my permission to let you rush off and write something, so why I shouldn’t say yes? It has not tested in any way at all, my desire to purchase from you.

The result from his single question is many fruitless hours putting together proposals in which your potential buyers have absolutely Zero interest. That's why its such a poor question.

If you can't resist asking this question, then at least have a good follow up question. This follow up question will help you stop becoming a work creation scheme. It goes like this "Thanks for allowing me to provide you with a proposal, can we arrange a short meeting in a couple weeks time to review it"? If and only if they agree to that meeting is it worth your while writing them a proposal.

The next time you are tempted to ask a prospect "Can I write you a proposal?" remember on its own it’s probably the worlds’ worst sales qualification question. So don't waste your or your sales teams’ time pointlessly knocking out proposals, get a commitment from your prospect first.


Exigent Consulting provides specialist services for Managing High Growth, Business Turnaround, and Mentoring to the Small and Medium Business. We help business owners improve the profit performance of their business. 


Friday, 6 September 2013

Good Culture and Return On Investment


There has been a lot in the press and blogosphere recently about how its people that matter in providing a competitive advantage to a business. In a recent discussion with a number of  high growth companies, whilst there was a general acceptance that people and more specifically Culture mattered; there was a mixture of both skepticism and confusion about how one might quantify the benefits. 
Good Cuture
Buddhist Flags Tibet

I went away to think about how I could use simple recognisable examples to demonstrate the economic value of "good" culture over a "bad" culture. 

Lets take two examples. The first is a company which might be described as having a bad culture or perhaps a culture where the employees don't feel engaged or committed to the business. I expect we can all recognise similar companies.

In this business employees turn up for work between 8 and 9 am but do not voluntarily start their work and continue to read their newspapers or use their smartphones until 9am. During the working day they stick religiously to the rules having 15 mins break in the morning and having their 1 hour lunch break. At the end of the day to make sure they can leave at 5pm exactly, consequently work winds down around 4:45 and everything is put away, necessary ablutions done in time for a mass exit at 5pm.

In the second business where they have a "good" culture staff arrive between 8 and 9am and mostly start their working day when they arrive, whilst everyone takes a lunch break many can be found back at their desks working resulting in them having substantially less than the mandatory hour. When 5pm arrives most of the staff are still working and they gradually drift away from work over the next  hour.

So its easy to see that on average people in the company with a "good" culture or where they are engaged with the organisation work longer. For the sake of this example lets assume that on average the "good" culture business get 30 minutes more per day per employee than the business with a "bad" culture. Based on my everyday example I don't think that's an unreasonable estimate to make.

Over a week that's 2.5 hours per employee on the basis that an employee works 46 weeks a year, excluding holiday entitlement and public holidays, that equates to 115 hours per employee per year or if you prefer about 16.5 days.   

For a company with 10 employees that's 165 extra free days work or 33 man weeks. That about 3/4 of a full time employee every year for a 50 man company that's 3.5 man years of effort extra.

So what does that mean in financial terms. That's a bit more difficult to quantify because were are going to have to make some assumptions about average pay across the business. Using composite rate of £10 an hour, which I suspect is a little conservative but makes the maths easier, we get an economic benefit of about £1150 per employee per year. For our 10 man company that £11500 per year. For our 50 man company that's £57500 comfortably more than a couple of employees. If we assume the businesses are in aerospace, IT or other high skilled industries the financial benefit increases dramatically because the average hourly rate is probably closer to £25 than £10.

So what have we discovered? Firstly I would say small differences matter 30 minutes a day isn't much spread across employees but it adds up to a significant extra saving and competitive edge. Secondly, in keeping this example as simple as possible we have ignored a number of other benefits including the fact that people work harder and more effectively when they are happy at work. They don't "clock watch", they operate better as a team. All these additional factors increase productivity and performance. They are however very difficult to quantify and certainly not without an organised an scientific study which is way beyond my capabilities. 

Nevertheless I think it has been possible to demonstrate clearly that there is a quantifiable benefit to having a "good" culture and even on this anecdotal basis its financial benefits are not to be ignored.


Monday, 15 July 2013

Recruitment is Key to Small Business Success


Recruitment of new staff is a big investment and full of risks; getting it wrong for any small business and especially for micro businesses, that is less than 10 staff it can be catastrophic. Despite this, for most small businesses the recruitment process, if it exists at all, is chaotic and usually based on he or she was cheap,  or they were recommended by a mate I trust.  Why do we do this, for the most part its because the business owner has little or no experience of recruitment and there is little trust in recruitment companies or the service they provide. 

English: Recruitment Process Map
English: Recruitment Process Map (Photo credit: Wikipedia)
So what can we do to reduce the risks. In preparation for recruitment of a new employee, as the owner of a small business you should have two things; a job description so you know what role they fulfill and a list of competencies that you think the person requires to be good at their job. So for example if you are employing a receptionist, they should be helpful, polite, have easy to read writing for reading notes, and a voice which is easy to understand over the phone.

Armed with this information you now have some criteria you can investigate when interviewing during the recruitment process. I can already hear some of you saying its a receptionist I haven't got time for that. I have two answers firstly, the receptionist will be the first point of contact for your business for your customers and prospects having a receptionist who is short tempered or even rude can have a serious impact on your business. Secondly, if you were spending £14000 and upwards on a machine I'm sure you wouldn't go and pay for it without bothering to check if it could do the job.

The first thing to ask I would suggest, which may come as a surprise to many, is will this person fit into my organisation. Whilst capability and relevant experience is very important making sure they will work well within your small team is very important indeed. Recruitment of a disruptive employee can do a lot of damage to both morale and productivity whilst at the same time take up a lot of management time and it may take several months for the business to recover. As you might expect the smaller the firm the bigger the level of disruption. 

Having decided on fit, my second suggestion is that you interview more than one candidate, this at least gives you some context for your decision to recruit. Often I have found that the comparison candidate has turned out to be the best fit for the business. 

Thirdly, make sure you ask all the candidates the same key questions during the interview, so you have some consistency in your feedback information and that you take notes so that you can compare the candidates. This is particularly useful. When there is some time between the two meetings. You'll be surprised how unreliable your memory can be especially with details.

Fourthly, do the unexpected during the interview as it helps you get valuable information, for example don't ask the typical questions like "tell me about yourself". Ask instead "what is the one thing you've done to date that you're most proud of or regret the most?" A key characteristic of a good employee is the ability to think "on their feet", you'll find more about a person by throwing a "curve ball" than you will by asking the predictable.  I recall one colleague deliberately made the first interview with a potential recruit as chaotic as possible to keep them off balance. I wouldn't necessarily recommend this extreme interview strategy but as a small business going through the motions at interview will increase the likelihood of a poor result.

Lastly and a very common stake made by small business owners, don't take a candidate just because they are the only one you can find. I've heard all sorts of rationalisations from business owners why they should take the person even though they may not be "perfect". 

For a high growth business keeping the up quality of your recruits is a vital component of continued success, keeping the quality level high for new employees is a key success criteria. If you can't find what you want, I'm afraid that taking the "next cab off the rank" is rarely a satisfactory solution. 

Exigent Consulting provides specialist services for Managing High Growth, Business Turnaround, and Mentoring to the Small and Medium Business. We help business owners improve the profit performance of their business. 


Friday, 17 May 2013

Eight Tips for Small Business Owners


This month I have a guest blog from a writer at Nerdwallet. Since I have so many US readers I thought It might be nice for you to get a more local view of the issues surrounding Small Business. Having said that Angie provide some useful common sense advice that is valuable to any small business; especially those who are about to, or have just started as business owners.


"Let’s be honest, owning a small business nowadays is challenging. There are so many things to keep in mind, and as such, many variables to consider. It can get a bit flustering trying to sort out every piece of advice you hear. Let’s look at eight solid guidelines that should be staples of any small business owner’s, “things to remember” list.

1. Save up as much money as you can before starting.

One of the worst mistakes you can make is going into business with no capital saved up. Relying on loans from the bank, the SBA or friends is a great way to get you into debt. What some small business owners don’t realize is that it can take awhile for your business to start providing enough profit for you to pay the loan(s) back. If you business isn’t as profitable as expected your lender might just call in the loan, or you may have to pay it off with your credit card. Save enough to cover yourself for at least a year after you start your business.

2. Minimize costs.

Calculate out how much everything is going to cost you. Find how out how little you could possibly spend, and still be effective. Don’t rent out more space than you need, or hire more employees than you will need. You want to start small and keep your screw-ups small too. Give yourself time to learn and deduce the best way to go about things, before you shell out too much cash on this or that. It will save you money in the long run. 

3. Safeguard your personal assets.

You must understand that once you start a business, you are liable for all debts and judgments that it incurs. This can include any judgments from lawsuits against your business, taxes, loans, or money owed to renters. To protect yourself from having your personal assets seized, you will want to get business liability insurance. This alone will not cover you against everything however, and you may want to consider forming a limited liability company.

4. Know how your business will be making a profit

You are going to want to crunch the numbers, analyze the data, and come up with a figure of how much you will be making, how much of it will be going back into the business, and how much actual profit you will be earning. Don’t forget to factor in all the costs of running your business, and figure out how much product you will need to sell.

5. Find your competitive edge and use it

Not every small business is successful, the ones who are doing things that nobody else is, or doing them better than anybody else is, are the ones who make the profit. Whether it’s a special marketing technique, survey method, or manufacturing short cut, find something you can use that nobody else is. You either have to have higher quality than your competitors, or be smarter than them. Once you find this competitive edge, it’s important to guard it. Don’t let anybody find out your secret to success, because it won’t be a secret anymore.

6. Put everything in writing

Oral agreements or deals made over handshakes are not reliable nowadays and it’s wise to put everything important in writing. Make a habit of giving and getting receipts for everything. You will need many contracts written up for things including storage agreements, service contracts, and leases. Don’t be the guy in court without any paper evidence of your claims.

7. Acquire quality employees

Hire employees who are both enthusiastic and highly skilled at their job. An enthusiastic employee will make your business environment much more friendly and appealing to customers. You want your employees to represent your company well on and off the job, and this is more likely to happen if your business is respectable. Pay your employees well and treat them with respect, the result will be worth more than the effort.

8. Pay your taxes! 

As a business, you will be responsible for more than just your personal taxes. Especially important to pay on time are your payroll taxes. These can levy heavy fines if not paid on time. Stay up to date on everything you owe, and maybe even pay some bills early once in a while, it will pay off for your reputation.


Angie Picardo is a staff writer for NerdWallet. Her mission is to help consumers stay financially savvy, and save some money with the best online checking account."


Exigent Consulting provides specialist services for Managing High Growth, Business Turnaround, and Mentoring to the Small and Medium Business. We help business owners improve the profit performance of their business. 


Monday, 8 April 2013

Finding Your Vision? Why Is It So Difficult?


I was doing some research for a book I am writing, part of which is about the importance of having a vision. What has become clear, especially in the UK, is how little understanding there is about this topic. This was brought more into focus whilst watching the documentary series "The Men Who Built America", what made them stand out was not only the strength of their Vision but the fact that they had one at all.

My experience in the UK with owner businessmen, is that it is quite challenging getting them to understand how important having a vision is to the long term prosperity of their business. When I give training courses about leadership of high growth businesses, the section on Vision is one of the most challenging. This is because I can count on the fingers of one hand how many business owners actually have thought out what their vision is, whilst the majority just dismiss it as some sort of consultant "mumbo jumbo".  They simply don't get it.

English: DOE Departemental Enterprise Vision
English: DOE Departemental Enterprise Vision (Photo credit: Wikipedia)
I wonder if it’s something about the British and their cynicism that prevents them from grasping the value of understanding the purpose of their business. I don't mean from a personal perspective ie to make money, retire in 5 years, those statements are just measurements. I mean having a real business Vision:  something that describes what it is about the way you do what you do, that will have customers flocking to buy your product or service. To paraphrase a comment about George Bush senior and his struggles with the vision thing "If you don't know where you want to go why would you expect others to put themselves out to help you get there?"

That’s essentially the simple great benefit of having a vision. It is something that you can use to bind your employees and your customers to you as they will see, understand and share your Vision and as a result will want to continue to be your customers or employees, to help you get there.

Most of us haven’t found that vision or purpose and so it is much easier to find a substitute and embrace someone else’s, rather than to try to uncover your own. By finding your vision you become one of the few and really separate yourself from your competition. Once found, it immediately makes decisions easier by simply asking does doing this move me towards my vision? You will instantly discard those actions to which the answer is “No”, allowing you to concentrate on those things that will. This immediately makes your business more effective, as you have a clear simple process on which to test effort and separate yourself from those who don’t know where they are going, so, do everything “just in case”

Let’s be honest, uncovering your vision is difficult and getting it down to a succinct phrase takes a lot of effort. Do you really think that the famous Disney vision "to make people happy" came together in a blinding flash? It was developed and honed over time to something that encapsulated the Vision in a simple sound bite. 

Just because we don't generally think at this level or in these terms doesn't mean we can’t if we don't put our minds to it. The first stage is to just put something down and work on it over time until you think it reflects your purpose.

Here are some examples of small business visions, but not small, business visions. I asked the members of the LinkedIn group that I run “managing high growth” if they had a vision and if so what it was. These were the results. I think these examples are more relevant than those famous Visions of the large corporates.

In case you’re asking mine is "To enable high growth businesses to grow faster for longer and with less stress" Others are “To help clients increase sales and reduce time and cost” and “To create an environment where people feel valued”

So uncover your vision and get yourself clarity in your business, separate yourself from your competition and start being more successful. If you think you'd like some more help in extracting your vision contact me here


Exigent Consulting provides specialist services for Managing High Growth, Business Turnaround, and Mentoring to the Small and Medium Business. We help business owners improve the profit performance of their business. 


Wednesday, 30 January 2013

The Five Most Common Mistakes when Buying or Selling a Business

  If you haven't been to my blog before you might want to subscribe to my feed
For most business owners buying or selling their business is a rare event indeed. In fact many owner managed businesses do it only once, when they exit their business to retire. Like most things in life the first time you do something is the occasion when you make the most mistakes. If you are selling a business you can't afford to make mistakes because its the only chance you'll get.

When buying a business  making a mistake can leave you not only seriously overpaying for a business but having a management headache which may take years not months to put right and in the meantime will seriously damage the prospects of your current business.  

It may be some comfort to know that it is not just smaller businesses the make horrendous mistakes, big businesses all too regularly fall into the same trap. I know from personal experience the the business I worked for in my last corporate role was purchased by another company and the acquisition almost brought the acquiring company to its knees, because as far as I could see it made two of these common mistakes.

Mistake No1 Getting emotionally involved with the sale.

Mistakes in Buying a business
SOLD! (Photo credit: my_new_wintercoat)
Lets face it, its exciting to be buying or selling a business and it requires a lot of management time. For the vendor selling a business  there is the prospect of making that exit and having the money to retire. For the buyer there is the undoubted prestige of acquiring a business and the prospect of a big jump in company size or new geographic coverage.

The result for the unwary buyer is that in buying a business they get duped into paying too high a price because they get wrapped up in the chase. For the novice seller the process of selling the business gets dragged out over a long period of time, causing them to take their eye off the day to  day management of the business, often leading to a downturn in its fortunes and so its ultimate price. 

Mistake No 2 Not Having a Walk Away Number

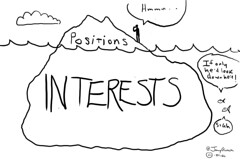
Have a walk away number
Negotiation Cartoons: Positions Vs. Interests (Photo credit: jonny goldstein)
Buying or Selling a business involves negotiation, in order to make sure you don't pay too much when buying a business or get paid too little when  selling a business you need to establish 1. what is the value of the business and 2. what is the maximum you'll pay or minimum you'll accept. Once you've established this you'll be much better placed in the negotiation and you'll be less likely to make mistake No1


Mistake No 3 Not understanding the Impact of Culture 

This Ladies and Gentleman is the big one, of all the issues that get overlooked culture stands head and shoulders above everything else. Good businesses have strong cultures, their staff have bought into the fact that their way is the right way. Now imagine what happens when these staff are told, that their way is no longer the right way and your way is the right way. Yes that's right they'll find every reason to demonstrate the flaws in your system and why your way is not the right way. Worse they are butting up against your staff who are equally convinced that your way is the right way. So you tend either to have a very difficult integration problem because you now have two opposing camps or you have an attrition problem as the staff from the acquired company leave.

The seller will of course say that culture isn't a problem, because to him it isn't. Either there isn't a problem with culture or its too late for you when you find out there is as he's already got his money. Why don't people address this problem? Firstly because so many don't even recognise it as an issue and secondly because the have made mistake number 1 and are looking for reasons to buy rather than looking for issues.

Mistake No 4 Underestimating Management Effort

Buying a business is just the first step, now you've got to integrate it with the rest of your business so that means addressing, culture, strategy, planning, financial systems, sales, customer relationships a new organisational structure to mention just a few. The management effort to achieve this is considerable even if you have willing staff , so don't be surprised if it takes 6 months to a year to get it all bedded down. This effort is considerable even if the new acquired company is small in comparison to yours.

 Mistake No 5 Buying a business that is too big or too small

This tends to relate to the problem of biting off more than you can chew. Remember the bigger the business you buy in relation to you the acquirer the more political clout it will have and the more concessions you will have to make, and the longer integration will take. The more your management is focused on the acquisition the bigger the risk that they will let your core business slip and then you have a really big management headache, that is, trying to integrate the new business and recover your own.

The other side of the coin is that you waste your money on something too small which won't payback a recent return on all the management effort required to integrate it into your existing business.

Once you understand these problems you are on your way to avoiding them and making your acquisitions a success and not a millstone.


Exigent Consulting provides specialist services for High Growth Businesses, Business Turnaround, and Mentoring to the Small and Medium Business. We help business owners improve the profit performance of their business. 


Thursday, 25 October 2012

Get Profit from your Sales

  If You Haven't been to my blog before you might want to subscribe to my feed

English: Cost-Volume-Profit diagram, showing b...
English: Cost-Volume-Profit diagram, showing break down of Sales into Contribution and Variable Costs. (Photo credit: Wikipedia)
A recent blog post on pricing reminded me that we tend to forget how important it is to make a profit and often how little room for manoeuvre there is when playing around with prices.

The average profit for all limited companies across the UK before 2008 was 7%, yes that's £7 out of every £100. I'll accept that many smaller businesses typically owner managed will depress their reported profits in order to reduce their tax liability.  Having said that there's not many businesses that regularly report profit before tax of 10% or better. What that really means is that pricing and getting it right is really important.

So point number 1 you need to understand fully what it costs you to produce your product or service. I don't mean guess it I mean know it intimately and in detail.  Recently I went to what appeared to be a reasonably successful retailer who were struggling financially. Superficially things appeared OK nevertheless I asked them to fill out a detailed spreadsheet itemising all their costs and not surprisingly their situation was much worse than they anticipated. What it had done was to get the business owners to focus on what it really took to run their business and that pricing was a much more important than perhaps they first realised, as a result now everything is priced on the basis that it makes a profit in its own right and in some cases that has meant a significant increase in individual product prices.

 For companies with a sales team, this message often gets lost, particularly as most sales people are rewarded against sales revenue and not profit per sale. Consequently if sales people are in a sticky position they automatically reach for the price lever and drop the price, after all a 10% discount on a 100k sale is only 10K  and that's relatively easy to find. The fact that it may have completely wiped out the profit on the sale is not on their radar.

So point number 2 get your sales team to focus on profit and not turnover. How can yo do this? Well how about giving them a little bit of training so they understand the mechanics of the business, and you could reinforce this by rewarding them on profit not turnover.

I've only be able to do this once but boy is the impact immediate. No more is there the argument that we had to sell this with a big discount to give us a foothold in this new account, nor is there the plea that "if I didn't give him that discount(and its usually a big one) we wouldn't have won the sale."  Why, because sales people don't want to go through all the effort needed to win a sale and end up getting no commission.

Interestingly what you do get are rather more searching questions like what does it cost us so much make this stuff, what else can we offer if we cant move much on price? This should lead both you and your sales staff to examine and really understand your company's value proposition and discover how to best promote them, which is no bad thing.

The important messages are that as a business owner, profit should be your prime motivator when selling. In order to do this you need to understand what your true costs of production are before adding in your profit and only after that setting your price.

Motivating your sales using profit has some beneficial side effects in forcing them and indeed to you really understand and to be able to justify why you sell what you sell at the price you sell it.

Exigent Consulting provides specialist services for High Growth Businesses, Business Turnaround, and Mentoring to the Small and Medium Business. We help business owners improve the profit performance of their business. 


Tuesday, 2 October 2012

Pricing objections - what they really mean

  If You Haven't been to my blog before you might want to subscribe to my feed

Pricing is perhaps one of the most misunderstood issues in business, if used properly it's one of the simplest ways to help you maximise your profits. Easy then, so what's the problem?

The problem with owner managed business is that they assume that they must be the cheapest to survive and are often very reluctant to raise prices, even in the face of ever rising overheads, just think of energy, fuel and courier(UPS) costs to mention a few. If I had a £1 for every time I've heard a company owner say "if I raise my prices I'll lose all my customers so I have to keep them as they are" I'd be very rich – sadly I'm not.
Gas Prices Are Up!!! Feelin' the Pinch...
Gas Prices Are Up!!! Feelin' the Pinch... (Photo credit: Clan UiBriain)

Why do so many people think like this? Much of it is conditioning, whenever we are not satisfied with a company for whatever reason we complain about the price. 

Let me give you some examples:

You're visited by a salesman who can't articulate the benefits of his product. 
What do you tell him when he asks for the business,"I'm sorry but I don't see a reason to buy this" or do you say "I'm sorry but it's too expensive".

You're visited by a salesman who you just don't like. What do you tell him when he asks for the business,or do you say "I'm sorry but I just don't think you're trustworthy" or do you say "I'm sorry but it's too expensive".

You're visited by a salesman who just doesn't get the point you're trying to make. What do you tell him when he asks for the business, "I'm sorry but you don't understand my problem so I'm not interested" or do you say "I'm sorry but it's too expensive"

You're visited by a salesman who's too pushy. What do you tell him when he asks for the business, "I'm sorry but you're the last person I'd buy anything from" or do you say "I'm sorry but it's too expensive"

You should be getting a message by now pricing is rarely the issue, price objections are mostly a cover for some other objection. So what does this tell us? The first thing is that raising your price is nothing to be afraid of. The second is that if pricing is seldom the real issue, raising your prices even in a recession wont frighten off your customers. Why? because the reason they are staying with you are not price related, it could be that you're convenient, they like you, they love your brand, you've helped their business, you are reliable, and so on....

So now you know let's look at what you can do. Well one thing you could try is to increase all your prices by 1% immediately. Why, because you can; if you're selling something for £100 pounds people aren't going to stop buying it because it now costs £101.

"I can't we're in the middle of the worst recession in living memory you must be nuts" – you say.

I say "no, its your conditioning that says that". 

I can in all honesty say that in almost every company I work with; one of the first things I do is to get them to increase their prices and having done so they are surprised that they don't lose any customers in the process. Yes even in the worst recession in living memory. Why? Am I a genius – I hope so – but no. Am I a magician – no. The answer is almost invariably, because most small companies are selling their product or service too cheaply because they've been conditioned to this as those people who don't want to buy from him use price as the objection.

Realistically as a small business owner you should understand that price is only factor among many people assess before purchasing and its by no means the main factor. Your price should reflect your costs and be sufficient to give you a decent profit. In order to price correctly you should have a detailed analysis and understanding of your costs. This is something that many businesses don't have. Only by understanding what and how your costs are made up in detail can you accurately set your prices over the long term. Whilst the general rule with pricing is that your sales price is 2.4 time manufacture costs, it's still a rule of thumb and likely to lead to a guess-timate of costs which will almost always be less than the real costs.

You should be increasing your price at a minimum annually to keep in step with the inevitable rise in your costs and additionally if there is a major change in the price of components. Don't worry if you are not the cheapest because it is rare that you will be as there is always likely to be a business with a lower price. Anyway you don't want to be the cheapest because down there is no customer loyalty.

So remember that pricing objections are more likely a cover up for other deficiencies, so don't be afraid to raise your prices and ask those price objectors what they're really unhappy about.

Exigent Consulting provides specialist services for High Growth Business , Business Turnaround, and Mentoring to the Small and Medium Business. We help business owners improve the profit performance of their business. 


Thursday, 23 August 2012

The Stresses and Challenges of Managing a High Growth Business

  If You Haven't been to my blog before you might want to subscribe to my feed
Choosing to follow a path of high growth is not always a conscious decision. I have met many businesses who find themselves in a phase of high growth and whose owners are looking around wondering how they got there. However in order to continue to achieve high growth they must get to grips with the business and understand why they are successful. This can be stressful in its own right because, if they don’t know why they are successful, they won’t know what to do to rectify the situation if things suddenly start to go wrong.

Operating in a high growth environment is living with relentless pressure, as high growth will seek out any weakness in a business and magnify its defects until resolved. The pressure for all high growth businesses owners is akin to that of patrolling the perimeter of a large defensive position, where one is constantly on the lookout for breaches and attempting to repair them as quickly as possible to prevent further problems later.

One of the most common causes of stress is where the owner is not in full control of the business. I often recognise this when the owner comes out with statements like “I feel the business is running me” or “I’m running through treacle, the harder I work the less progress I make”. As decisions and issues pile up, the business owner starts to become more and more reactive and as such, loses the ability to direct the business. Sadly this situation, if left unchecked, has only one result. There will come a point where the backlog of issues create a tipping point and the wheels come off; often in the most spectacular way, with growth hitting a virtual brick wall resulting in little, none or even negative growth in the following 12-18 months.

Another common reason for stress in high growth businesses is that the underlying rate of growth in the business tends to towards a similar rate of change as new positions, recruitment, and management structures are implemented to support the underlying growth. This means a lot of decisions have to be made to drive the business forward and the business owner will, without doubt, make some bad decisions. This in itself creates the need to take more decisions to correct mistakes. Many business owners need to realise that it is more important to make a decision even though it might be wrong, than to sit on it and hope the problem goes away. It never does, and like many things in life, consciously doing nothing only makes the situation worse.

The key challenge for any high growth business is for the management to be able to look forward and foresee potential issues and problems. In order to do this effectively a number of things need to be in place, the business needs sufficiently detailed information to understand and monitor the key linkages in its business and that this information is available in a timely manner. By that, I mean very quickly. In the business I worked in, for example, we had what we called a flash (rough cut) sales figure for the previous month available on 1st of the following month. Detailed management accounts were available by the end of the first week of the following month.  For many businesses this might either been seen as the Holy Grail or unnecessary, but it is fundamental to the success of a high growth businesses.

One of the less obvious but nonetheless significant challenges to assist management to look forward and make the appropriate decisions is one of culture. A healthy culture is absolutely fundamental to a successful high growth strategy, as individuals and teams need to grow rapidly to support and continue to promote the strategy of business growth. Staff and management will be in an almost continuous state of learning and development – that means more mistakes. In order to learn and develop, the culture must promote a team approach and not condemn people for getting things wrong. In a recent article I explained at last that there were hard numbers which reinforce what we always suspected; that healthy cultures deliver better business performance.


This article might have given you the impression that you would have to be slightly mad to want to choose a high growth strategy. There is no doubt that a high growth environment is a challenging place to be, it does however have its rewards for those who successfully master the conditions. Those who succeed in a high growth environment represent the best of business leaders and managers and whilst successful high growth businesses represent only 6% of all businesses in the UK, they contribute 45% of UK employment growth. Such companies are a vital resource, that need to be supported and encouraged and whilst difficulties are many the potential rewards are much greater.


Exigent Consulting provides specialist services for High Growth Business, Business Turnaround, and Mentoring to the Small and Medium Business. We help business owners improve the profit performance of their business.